
Why Is Your Medicare Premium Higher Than Expected?
If you’ve ever opened a Medicare premium notice and found a number higher than you expected, IRMAA may be the reason.
The notice can be confusing because this adjustment is separate from the standard Medicare premium. It can affect Part B and Part D, while Part A costs are based on work history rather than income. The sections below explain how the adjustment is calculated, what income can trigger it, and when you may be able to request a new determination.
What Is IRMAA in Medicare?
IRMAA (Income-Related Monthly Adjustment Amount) is an extra amount added to your Medicare Part B premium, and Part D premium if you have drug coverage, for people whose income is above a certain level. It’s based on your Modified Adjusted Gross Income from two years earlier, reassessed annually, and can be appealed if your income has since changed.
How Is IRMAA Calculated?
Your Modified Adjusted Gross Income, or MAGI, includes more than just the adjusted gross income line on your tax return — it also picks up things like tax-exempt interest, municipal bond interest being a common example.
Here’s the part that catches people off guard: the brackets work on a sliding scale, and they’re set up as a “cliff” rather than a gradual phase-in. That means crossing into the next bracket, even by a small amount, can trigger the full surcharge for that tier rather than a partial one. This is also why a one-time event — selling a home, a large retirement account withdrawal, a Roth conversion — can trigger IRMAA even for someone who wouldn’t normally be affected by it.
IRMAA applies whether you have Original Medicare or a Medicare Advantage plan, since it’s added to the underlying Part B (and Part D, if applicable) premium either way.
What Income Triggers IRMAA?
Social Security and CMS publish updated income brackets each year, and where your income falls on that sliding scale determines whether — and how much — IRMAA applies. Because these thresholds and surcharge amounts change annually, we’d rather help you check your specific numbers than list a figure here that may already be outdated. Medicare.gov and Social Security’s own IRMAA pages keep the current-year brackets up to date, and we’re happy to help you make sense of where you land.
What matters more than memorizing a threshold is understanding that IRMAA is based on income, not on which plan you choose or how many services you use. Two people on the exact same plan can pay very different premiums depending on their income from two years prior.
Beyond IRMAA: Premiums, Deductibles, Copays, and Out-of-Pocket Costs
IRMAA is one piece of a bigger picture. Understanding your full Medicare costs usually means looking at a few things together:
- Your Part B premium (the base amount IRMAA is added on top of, if it applies to you)
- Part A and Part B deductibles, which you typically pay before Medicare starts covering a service
- Premiums for Medicare Advantage, Medicare Supplement, or Part D, depending on the coverage you choose
- Copays and coinsurance for doctor visits, procedures, and prescriptions
- Whether your plan has an annual out-of-pocket maximum — Medicare Advantage plans generally do, while Original Medicare on its own does not, which is one reason many people pair it with a Supplement plan
How these pieces add up depends heavily on the type of coverage you have and how you use it, so two people can have very different total costs even with similar incomes. This is usually the point where it helps to sit down and look at your specific situation rather than trying to estimate it from general numbers.
Can You Appeal an IRMAA Determination?
Yes. If your income has genuinely changed since the tax year Social Security used to calculate your IRMAA, you can ask for a new determination using Form SSA-44, rather than waiting for it to correct itself in a future year.
This process is specifically for a change tied to a qualifying life-changing event, which generally includes things like:
- Marriage
- Divorce or annulment
- Death of a spouse
- Work stoppage or retirement
- Work reduction
- Loss of income-producing property
- Loss of pension income
- An employer settlement payment
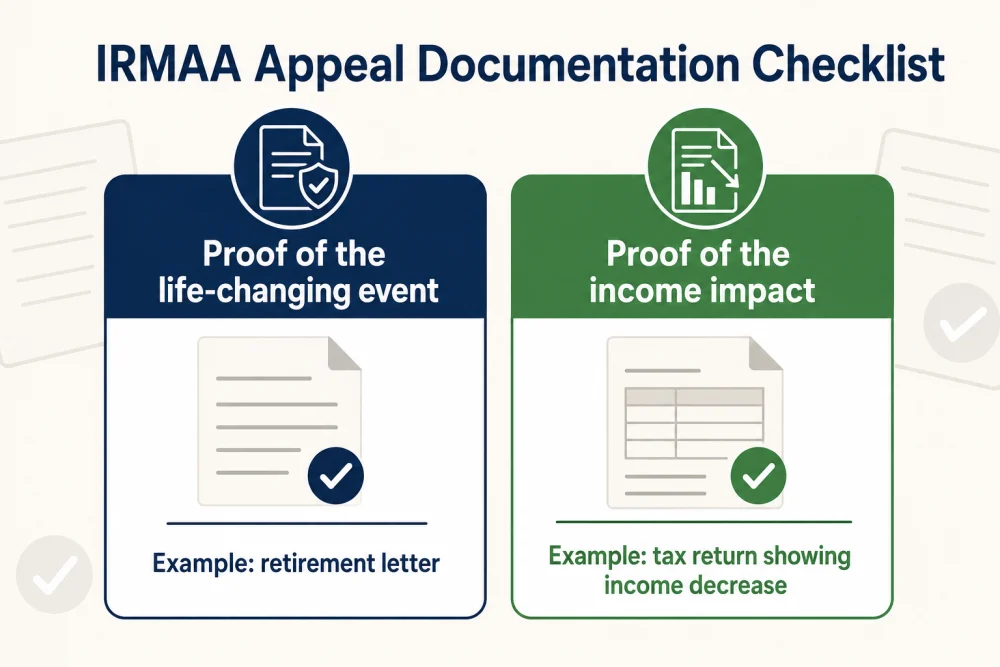
You’ll need to include documentation of both the event itself and how it affected your income — for example, a retirement letter from your former employer along with the tax return showing the income drop.
Processing times vary. If Social Security approves a new determination, the effective date depends on when the request is made and the circumstances of the income change.
Not ready to book a full consultation but have a question about your own situation first? Talk with a local Medicare advisor.
Ways to Manage or Lower Your Medicare Costs
There’s no single trick that lowers everyone’s Medicare costs, but there are a few things worth understanding as you look at your own situation:
- Reviewing your plan choice periodically — the right fit between Medicare Advantage, Medicare Supplement, and Part D can shift as your health, prescriptions, or budget change
- Checking whether you may qualify for Extra Help or a Medicare Savings Program, which can reduce costs for people who meet certain income and resource limits
- Comparing your options during enrollment periods rather than letting a plan auto-renew year after year without a second look
- Filing for an IRMAA redetermination if a life-changing event applies to you, as covered above
None of this guarantees a lower bill — your situation, your income, and your coverage choices all play a role — but understanding the moving pieces is usually the first step toward finding what may work better for you.